Renting or buying: the simple version
Renting in Montréal or on the South Shore and wondering if it’s time to buy a condo? There is no universal answer. Both options can make sense.
When you rent, your monthly payment covers a place to live, and your landlord handles major repairs. When you buy, part of each mortgage payment goes toward paying down your loan, which slowly builds equity. In exchange, you take on new costs and responsibilities.
So the real question is not “is buying better than renting?” It is “am I ready to own, and does it fit my plans for the next several years?”
Your down payment: what the 5% minimum means
In Canada, the minimum down payment for a home you will live in is generally 5% on the first portion of the purchase price, with a higher percentage required on the portion above certain thresholds. The exact rules can change, so confirm them with a lender or mortgage broker.
- With less than 20% down, your mortgage usually needs default insurance (for example, through CMHC). The premium is generally added to your loan.
- A larger down payment means smaller monthly payments, but it is not required to get started.
- First-time buyers may be able to use tools such as the First Home Savings Account (FHSA) or the RRSP Home Buyers’ Plan. Eligibility rules apply, so check with your financial institution.
- Plan for more than the down payment: closing costs such as the notary, an inspection, adjustments and the welcome tax also need to be covered.
Get pre-approved before you start visiting
A mortgage pre-approval is a lender’s review of your income, debts, credit and savings. It gives you an idea of the amount you could borrow and, often, holds a rate for a set period. It is not a final approval, but it is the best first step.
Lenders also test whether you could still afford your payments if rates were higher, so the amount you qualify for may differ from what you expect. Rates change often, so ask your lender for current numbers.
One tip: the maximum you qualify for is not necessarily the amount you should spend. Choose a monthly payment you are comfortable with.
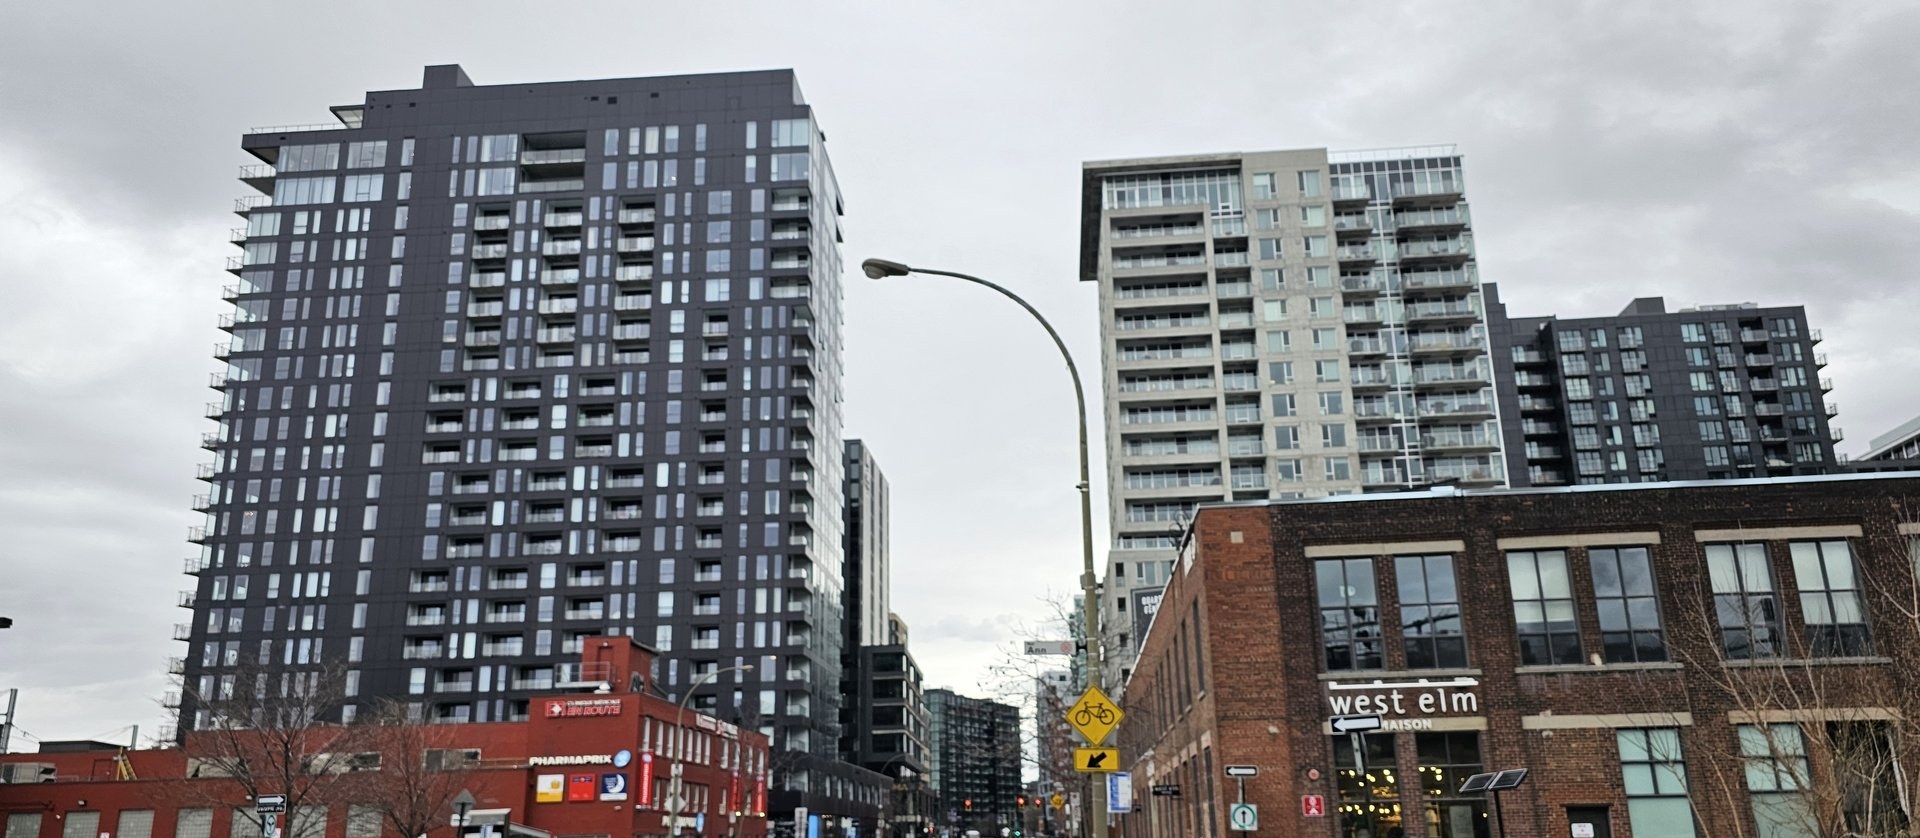
The monthly costs of owning a condo
Before comparing with your rent, add up all the regular costs:
- Condo fees: paid monthly to the syndicate of co-owners. They cover building maintenance, common-area insurance and contributions to the contingency fund. They vary a lot from one building to another.
- Municipal and school taxes: billed every year based on the property’s assessed value.
- Co-owner insurance: covers your unit, your belongings and your civil liability. The syndicate’s policy does not replace it.
- Utilities and upkeep: electricity, internet, and repairs inside your unit.
Also ask about the health of the contingency fund and any planned work. A well-funded building reduces the risk of a surprise special assessment.
Don’t forget the welcome tax
In Quebec, buyers pay property transfer duties (droits de mutation), commonly called the “welcome tax.” It is charged by the municipality, calculated in brackets based on the purchase price, and billed a few months after you buy. It is not included in your mortgage, so plan for it in your savings. Some municipalities offer programs for first-time buyers, so check what applies where you are buying.
A simple 5-step readiness checklist
- 1. Your income is stable. You expect your work situation to stay steady for the next few years.
- 2. Your down payment and closing costs are saved. Including the welcome tax, with an emergency cushion left over.
- 3. Your debts and credit are under control. Credit cards and loans are manageable and your payments are on time.
- 4. You know your full monthly budget. Mortgage, condo fees, taxes, insurance and utilities, compared honestly with your rent.
- 5. You plan to stay a while. Buying and selling have costs, so owning usually makes more sense if you plan to stay several years.
If you check most of these boxes, you may be closer than you think. If not, that is useful to know too. It shows you what to work on.
Let’s talk, with no pressure
Looking at the South Shore? Take a look at Saint-Constant.
Going from renter to owner is a big step. If you’d like to review your situation or understand how buying works in Montréal or on the South Shore, I’m happy to talk. No commitment, no pressure. Just clear answers.
Ready to see where you stand? Contact me through montrealimmobilier.ca for a no-pressure conversation about buying your first condo.
This article is general information only and is not financial or legal advice. Rules, rates and programs change. Please confirm your situation with a lender, mortgage broker, notary or other qualified professional.